The JSE has delivered strong returns, but the real question isn’t whether South Africa has good investments; it’s whether one small, concentrated market should carry your entire retirement.
Investors often ask me why invest offshore when you live in South Africa, earn in rand, and understand the local companies well?
It is true that the JSE has served investors well recently. Over the past 10 years, it has returned close to 12% a year in rand, comfortably ahead of local inflation. This performance means that R100 000 invested a decade ago in a JSE tracker is worth roughly R308 000 today.
Local assets are essential, for the simplest of reasons: your everyday expenses are in rands, and local investments are the natural match for them.
The real question to ask is not whether South Africa has good investments. It clearly does. The question is whether one relatively small, concentrated market should carry such responsibility for funding your retirement, protecting your buying power, and supporting the people who come after you.
In short, you need more than what the local market has to offer.
Read: When your wealth outgrows your borders
Your portfolio should not mirror your passport
Most South Africans already hold a significant bet on South Africa before they open an investment statement. They earn income in SA. Own a home in SA. Most of their retirement capital sits inside local rules and institutions, and most of what they will spend in future is priced in rand.
Filling the rest of your portfolio with more local assets doesn’t reduce that concentration, it adds to it.
Offshore assets work as a counterweight by investing in companies that earn across many regions, in several currencies, at different points in the economic cycle.
The risk in having a strong home bias isn’t that South Africa might struggle. It’s simply that too much of your financial life can rise or fall as a result.
A big fish in a small pond
Size is the first issue. The FTSE/JSE All Share Index holds around 119 shares. The MSCI ACWI, a broad global index, holds close to 2 461 stocks and still captures only about 85% of the world’s investable market.
It’s a well-known fact that South Africa makes up well under 1% of global listed equity.
Concentration is the second issue. The 10 largest JSE shares make up close to half the entire local market. Financials and basic materials alone account for close to 60% of the JSE, which leaves a local-only investor heavily exposed to a handful of banks and miners, the gold price, and the rand.
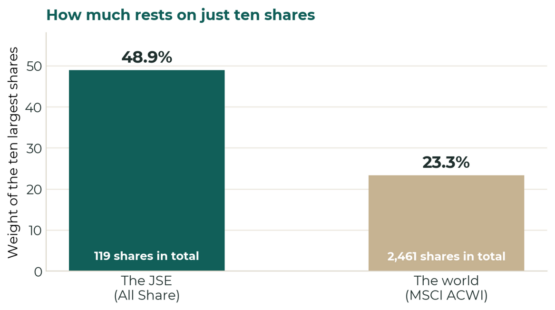
Weight of the 10 largest shares. Sources: FTSE Russell (FTSE/JSE All Share) and MSCI (ACWI), 30 June 2026.
The pond is shrinking too. The number of companies listed in South Africa has fallen from around 740 in 1990 to roughly 212 today.
Fewer listings mean fewer choices, and a greater chance that local portfolios crowd into the same handful of large shares, missing entirely the software, healthcare, semiconductor, and global consumer businesses that barely exist on the JSE.
Read/Listen: What really drives returns on the JSE?
This is not a bet against South Africa. It is a realistic view of concentration. South Africa is one country, one currency, and a narrow stock market, and your future is too important to depend on a single economic and political outcome, however familiar it feels. Invest locally where the opportunity is attractive and the expense is in rands. Invest globally because your wealth deserves more than one route to success.
The rand is a risk, and a diversifier
Currency isn’t the whole offshore story, but it can’t be ignored. In 2011, around R6.70 bought a US dollar. Today it takes roughly R16.50, a decline of close to 60% over 15 years, or about 6% a year.
This matters because so much of what you’ll eventually spend on, international travel, imported goods, medical technology, children studying abroad, is priced in hard currency.
As we all know, the rand can strengthen as well as weaken, and a stronger rand reduces offshore returns in the short term, so the aim isn’t to gamble on the exchange rate. It’s to avoid having every asset and every future expense depend on the same one.
Phasing money offshore steadily over time is a far more sensible approach than trying to time the perfect moment.
When you translate returns into a hard currency, the local picture shifts. Over the past fifteen years the S&P 500 compounded at close to 14% a year in dollars.
Measured in the same dollars, the JSE delivered far less, because much of its rand return was offset by the weaker currency. A few percentage points a year, compounded over fifteen years, becomes a very large difference in the end.
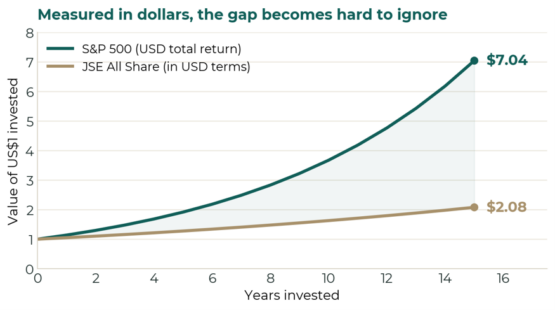
Illustrative growth of US$1 over 15 years. S&P 500 shown as USD total return; JSE All Share converted to USD. Start and end dates materially affect these figures.
The strongest objections, answered honestly
Here’s how I think about the most common concerns clients raise.
| What clients often say | The honest answer |
| “The rand looks too weak to send money out now.” | It may weaken further, or it may strengthen. Phase money offshore over time and anchor the decision to a long-term target, not a guess about the exchange rate. |
| “The JSE looks cheaper than global markets.” | Valuation matters, but cheap markets can stay cheap for years. Hold local value opportunities alongside global quality and growth, rather than forcing an all-or-nothing choice. |
| “Global markets are just a handful of US tech shares.” | That concentration is real and worth managing. Even so, global investing still opens up far more regions, sectors, and styles than a single local market can. |
| “But my expenses are in rands.” | True, and that’s exactly why you keep meaningful local assets. It isn’t a reason to tie your long-term growth capital to one economy and one currency. |
A more generous offshore allowance
In the 2026 Budget, the single discretionary allowance doubled from R1 million to R2 million per adult per calendar year, effective from April 2026. The foreign capital allowance remains R10 million per adult per year, subject to tax clearance.
Why this matters is that structure is as important as your decision to go offshore. A rand-denominated global fund isn’t the same as money physically externalised, even when the underlying investments look similar.
Read: Exempt at home, exposed abroad: Offshore wealth structuring for effective succession planning
Tax, estate planning, offshore situs exposure, platform costs, and access to capital all need to be weighed properly, and that’s exactly where I can help you choose the right route.


 Megan joined the Brenthurst Wealth team in March 2026 as an Administrative and Fiduciary Services Assistant at our Val de Vie Office in the Western Cape. Prior to joining Brenthurst, Megan gained three years of experience in the retail sector, where she developed management and client service skills.


 I obtained my National Diploma in Financial Information Systems from the Cape Peninsula University of Technology in 1999 and have worked in the wealth management industry since January 2000. Over the years, I have gained extensive experience in various roles, including Portfolio Manager Assistant, Planner Assistant, and Paraplanner.
 Esmarelda Isaacs-Andreas joined the Brenthurst Wealth Stellenbosch office in October 2025, taking on the dual role of Receptionist and Fiduciary Administrator.
 I obtained my National Diploma in Financial Information Systems from the Cape Peninsula University of Technology in 1999 and have worked in the wealth management industry since January 2000. Over the years, I have gained extensive experience in various roles, including Portfolio Manager Assistant, Planner Assistant, and Paraplanner.

 Ashley joined Brenthurst Wealth in January 2025 as Office Administrative Assistant and Receptionist for the Stellenbosch Office.


 René Heystek joined Brenthurst Wealth in November 2023, as receptionist and administrative assistant in the newly established George/Garden Route office.

 Michelle Heystek has built a career in the financial services over the last two decades, after obtaining her B.Com degree in Financial Management in 2005. Once she joined Brenthurst in 2006, she continued her academic journey, obtaining her Certificate in Wealth Management from INSETA in 2007, followed by a Postgraduate Diploma in Financial Planning from the University of the Free State. In 2008, she earned the Certified Financial Planner (CFP®) designation.


 Anelle joined Brenthurst Wealth as a Receptionist and Administrative Assistant to Brian Butchart in the Cape Town office in December 2023. She has a wealth of knowledge from working as a liaison between Financial Advisers and clients at TMA and Absa Investment Management Services (Aims) since 1998. She obtained her B. com degree from the University of Port Elizabeth in 1997.


 ADMITTED ATTORNEY | FINANCIAL PLANNER & HEAD OF BRENTHURST FOURWAYS


 Sanet was appointed in April 2020, joining our Cape Town team as an Executive Administration Assistant to Renee Eagar. She has been in the financial services industry since 1990. Her previous experience includes positions at Sanlam, BJM and ABSA. She spent her last 12 years working at Alexander Forbes Private Client Wealth as a Senior Wealth Management Assistant. She has received numerous accolades over the years which include but not limited to, Alexander Forbes Client Service Excellence – Silver award in 2014,2015 and 2017. Sanet has also obtained her Certificate in Wealth Management (NQF 5) in 2012 and achieved “Best Student of the Year” from Moonstone.


 Maria Smit is a Certified Financial Planner® with over 10 years of experience in the financial planning industry.